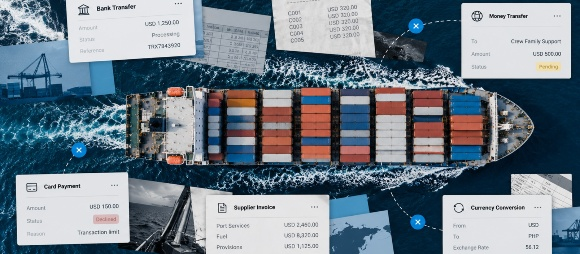
The hidden costs of fragmented maritime payments include the work around the transaction: entering information again, rebuilding its history and answering repeated enquiries. When procurement, finance and treasury work from separate records, even a routine supplier payment can require checking and correction.
Start with one purchase and follow the effort from order to reconciliation. Look for where someone must re-enter a reference, chase an update or investigate an unmatched payment. Those handoffs make administrative work visible and give the teams a practical starting point for improvement.
Repeated enquiries start before payment
Payment planning belongs alongside delivery planning. If a supplier requires payment before dispatch, procurement and finance need a shared understanding of when confirmation is needed and what confirmation the supplier expects. Where credit terms apply, keep the agreed due date visible with the purchase.
For example, consider a replacement component arranged for a vessel’s next port call. Procurement has the delivery arrangements; finance prepares the payment. In this example, the handoff is the agreed payment requirement, the relevant deadline and the person coordinating with the supplier. Do not assume that urgency around delivery makes every invoice an urgent payment. Missing payment requirements can turn a routine purchase into repeated enquiries and last-minute escalation.
Disconnected records create reconstruction work
Each record should help the next team identify the same transaction. Begin with the supplier, purchasing entity, vessel or business activity and agreed terms. Link the invoice to the order and, where appropriate, confirmation that the goods or services were received.
An approved invoice should inform payment preparation without unnecessary re-entry. Otherwise, a connection may move data while leaving people to check and correct it manually. Review the order, invoice and payment records together:
| Record | Connection to review |
|---|---|
| Purchase order | Supplier, purchasing entity, vessel or activity, and agreed terms |
| Vendor invoice | Related order and any relevant delivery confirmation |
| Payment preparation | Paying entity, beneficiary details, amount, currency and reference |
| Payment report | Related invoice and accounting record |
| Remittance advice | The payment and the invoices it covers |
Check exceptions as well as straightforward purchases. A payment may cover several invoices; a purchase may include a partial delivery, an advance or a credit note. The record needs to retain those relationships. A supplier’s trading name may also differ from the entity issuing its invoice, so a name alone may not be enough to follow the purchase.
Microsoft’s settlement documentation provides one example. Selecting invoices marks them for settlement against a payment. It also allows a posted prepayment to be marked against a purchase order, then settled against the invoice created from that order. These are software workflow examples of retaining the connection between an invoice, an order and a payment.
Unclear status creates more follow-up
An invoice awaiting approval, a payment scheduled for release and a transfer submitted for processing describe different stages. Submission does not necessarily mean the supplier has received the funds.
Microsoft’s payment-return documentation for the Norwegian version shows why status labels need context. A receipt return comes from the bank after the remittance file is sent; importing it sets the payment status to Approved. A settlement return comes after the payment is executed. The same documentation also describes rejected returns and warnings that require attention. These are labels and events in that particular software workflow. Teams should check what their own payment report confirms before answering a supplier’s enquiry.
An unclear update sends the enquiry back through the teams handling the purchase. When reviewing a status, ask what happened, what remains outstanding and whether further confirmation is needed. Procurement needs an update it can use for delivery arrangements and supplier enquiries. Finance needs the approval, execution and unresolved-item details. Treasury needs the timing of expected disbursements and the accounts involved.
Useful visibility does not require giving everyone the same payment permissions. Keep access appropriate to each responsibility, including who can change beneficiary details and release funds.
Unowned exceptions leave investigation work
A connection between systems is only part of the process. Establish which system owns supplier information, how invoice and payment references are retained, and how changes move between systems. Give missing records, rejected data and failed exchanges a clear route for follow-up.
For a missing invoice reference, identify the record that needs correcting and the team responsible for it. For an unclear payment update, establish what confirmation is available and who will obtain the next update. Keep that ownership visible to the teams handling the purchase and the supplier relationship.
The same applies during reconciliation. Assign unmatched items to an owner and retain the information needed to investigate partial payments, combined payments and returns. When a supplier asks for an update, the response should identify the current position and next step from the shared record.
Make the hidden work visible
Direct system connections may suit some operations; structured file exchanges may be a practical starting point elsewhere. Either approach needs consistent information, clear ownership and a way to identify exceptions.
Choose one recent purchase and follow its records together. Note where information was entered again, where someone reconstructed the payment history and which routine enquiries required further investigation. Agree who will resolve each gap. Assess progress through fewer duplicate entries, clearer responsibility and less time spent resolving routine enquiries.